Author: numan
What happens during the conveyancing process in the UK?
Buying or selling property is one of the most significant financial transactions most people will ever undertake. While estate agents negotiate the deal, the legal transfer of ownership is handled through the conveyancing process in the UK.
The conveyancing process begins when an offer is accepted and ends when the new owner is registered at HM Land Registry. Although it may seem administrative, it involves detailed legal investigation, contractual obligations and strict compliance requirements.
Understanding what happens at each stage can reduce stress and help avoid unnecessary delays.
What Is Conveyancing?
Conveyancing is the legal process of transferring ownership of property from one party to another. It applies to both residential conveyancing (homes and flats) and commercial conveyancing (shops, offices, warehouses and investment property).
The process is broadly similar whether buying or selling, but the responsibilities differ depending on which side you are on.
Versus Law handles both residential and commercial transactions through its specialist conveyancing services.
Stage 1: Instructing a Solicitor
Once an offer is accepted, both buyer and seller instruct a conveyancing solicitor.
The solicitor will:
- Verify identity and carry out anti-money laundering checks
- Confirm terms of engagement
- Request initial documentation
- Begin preparing or requesting the contract pack
For buyers, this stage often includes providing evidence of deposit funds and mortgage details. For sellers, it involves completing property information forms and providing title documentation.
Choosing an experienced firm is critical. Delays often occur not because of the legal system itself, but due to slow responses, incomplete documentation or poor communication.
Stage 2: Draft Contract and Initial Investigations
The seller’s solicitor prepares a draft contract and sends it to the buyer’s solicitor along with supporting documents.
These usually include:
- Official copies of the Land Registry title
- Property information forms
- Fittings and contents list
- Leasehold information (if applicable)
The buyer’s solicitor then begins investigating the title. This is a crucial part of the stages of conveyancing.
They will check:
- Ownership rights
- Restrictions or covenants
- Rights of way
- Lease terms (if leasehold)
- Planning history (via searches)
If anything is unclear or inconsistent, pre-contract enquiries are raised.
This investigative stage protects the buyer from inheriting legal problems.
Concerned about delays before exchange of contracts?
The period between searches, mortgage approval and final enquiries is where many property transactions stall. If your purchase or sale feels stuck, we can assess what stage your conveyancing has reached and identify what is realistically holding matters up — before completion dates are affected.
Discuss your conveyancing timeline
Stage 3: Property Searches
Property searches form a major part of the conveyancing process in the UK.
Common searches include:
- Local authority search (planning, building regulations, enforcement notices)
- Environmental search (contamination, flood risk, ground stability)
- Water and drainage search
Depending on location, additional searches may be required, such as mining or infrastructure checks.
Search results can take several weeks depending on the local authority. Delays at this stage are common and often outside the solicitor’s control.
Stage 4: Mortgage Offer and Survey
If the buyer requires a mortgage, the lender will issue a mortgage offer once satisfied with affordability and valuation.
The buyer’s solicitor must:
- Review mortgage conditions
- Ensure compliance with lender requirements
- Report any legal concerns
At the same time, buyers often commission a survey. While not a legal requirement, a survey identifies structural issues that may affect value or safety.
Importantly, solicitors do not advise on the physical condition of a property. Their role focuses on legal title and risk.
Stage 5: Report on Title and Signing Contracts
Once enquiries are resolved, searches returned, and mortgage conditions satisfied, the buyer’s solicitor prepares a Report on Title.
This document explains:
- What the buyer is purchasing
- Any risks or restrictions
- Financial breakdown
- Legal obligations
Both parties then sign their contracts.
The buyer also transfers the deposit — typically 10% of the purchase price — to their solicitor.
At this point, the transaction is ready for exchange.
Stage 7: Completion Day
Completion day is when ownership formally transfers.
On the agreed date:
- The buyer’s solicitor transfers the purchase funds
- The seller’s solicitor confirms receipt
- The estate agent releases the keys
Completion usually takes place around midday, once funds clear.
At this point, the buyer becomes the legal owner and can move into the property.
Stage 8: Post-Completion and Land Registry
Although keys have been handed over, the conveyancing process is not entirely finished.
The buyer’s solicitor must:
- Pay any Stamp Duty Land Tax (if applicable)
- Register the buyer’s ownership at HM Land Registry
- Register the mortgage lender’s charge
Land Registry processing can take several weeks or months depending on complexity.
Only once registration is complete is the buyer officially recorded as the legal owner.
If you’re new to property transactions, it may help to first understand what conveyancing means when buying a home.
How Long Does the Conveyancing Process Take?
On average, the conveyancing process in the UK takes 8–12 weeks for freehold properties and slightly longer for leasehold transactions.
However, timelines vary depending on:
- Whether there is a property chain
- Mortgage approval speed
- Search delays
- Complexity of title
- Leasehold management information delays
Commercial transactions can take longer due to additional due diligence.
For commercial matters, Versus Law also provides specialist support through its commercial conveyancing services.
Is Conveyancing Different for Leasehold Properties?
Yes. Leasehold conveyancing involves additional complexity.
The solicitor must review:
- Lease length
- Ground rent terms
- Service charges
- Management company obligations
- Restrictions on assignment
Delays frequently occur due to slow responses from managing agents.
If you are buying a leasehold flat or house, this will typically extend the overall timeline.
Commercial Conveyancing and Lease Transactions
In commercial property transactions, the process can involve additional considerations such as:
- Lease negotiations
- Rent review clauses
- Break options
- Dilapidations
- Security of tenure
Businesses entering into a commercial lease may wish to calculate potential costs before committing. Versus Law provides a commercial lease calculator to help assess financial implications.
Residential vs Commercial Conveyancing
While the fundamental legal structure is similar, residential and commercial conveyancing differ in risk profile and complexity.
Residential transactions focus on individual buyers and homeowners. Commercial conveyancing involves businesses, investment structures, and often higher financial exposure.
Versus Law handles both through its wider legal services offering.
For residential property matters specifically, you can learn more about their residential conveyancing expertise here:
Final Thoughts
The conveyancing process in the UK is structured, regulated, and legally significant. From instructing a solicitor to exchange of contracts and final Land Registry registration, each stage plays a vital role in ensuring property ownership transfers securely.
While the process can feel slow or complex, its purpose is to protect both buyer and seller from legal and financial risk.
Understanding what happens at each stage — and instructing experienced legal professionals — can make the journey smoother and more predictable.
From offer accepted to Land Registry registration — know where you stand
Every stage of the UK conveyancing process carries legal and financial consequences, from reviewing title and raising enquiries to exchange of contracts and completion day. Whether you are buying, selling, or negotiating a commercial lease, our team provides measured legal oversight to ensure each step is handled properly and without avoidable risk.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
What Is the TR1 Transfer Form?
What is the TR1 transfer form? The TR1 transfer form is the official document used to legally transfer ownership of a property in England and Wales when the whole registered title is being transferred. It is signed as part of the conveyancing process, dated on completion, and then used to update the title at HM Land Registry.
If you’re buying, selling, gifting, or changing ownership shares, this form is one of the key legal steps that makes the transfer “real” in law.
Because the Land Registry TR1 form is a deed, it needs to be prepared and executed correctly. Errors can cause delays, rejections, and unnecessary stress at the point you want the move to be finished.
What the TR1 Transfer Form Does
The TR1 transfer form is the legal “handover document” for property ownership. It tells HM Land Registry who is transferring the property (the transferor) and who is receiving it (the transferee), plus the title number, address, price (or gift), and any special terms.
Once completion happens, the buyer’s side normally applies to register the change. That’s how the register is updated so the buyer is shown as the new legal owner.
It’s worth being clear about one point: the TR1 is for transfer of whole. If only part of a title is being transferred, a different document is used instead.
When Do You Need a TR1 Transfer Form?
You’ll usually need a TR1 transfer form when the entire ownership of a registered property is changing hands.
Common situations include:
- A standard sale and purchase (seller to buyer)
- Gifting a home to a family member
- Transfer of equity (adding/removing an owner)
- Certain first registration situations where ownership is being transferred
In each of these cases, the conveyancing process uses the Land Registry TR1 form as the main deed that supports the registration change.
The TR1 form is one of several documents used during property transactions, typically appearing towards the end of the conveyancing process in the UK.
If you’re not sure which route applies to your situation, Versus Law’s conveyancing service can confirm what you need early, before paperwork starts causing delays.
What’s Inside the Land Registry TR1 Form?
Most people only see the TR1 near the end of a transaction, but it helps to understand what you’re signing. The Land Registry TR1 form is divided into 12 panels.
Below is what they mean in practical terms.
Panels 1–3: Identifying the title and the completion date
Panel 1 is the title number. If the property is not registered, this section is handled differently and the supporting application matters.
Panel 2 is the property description and address, usually matching the register.
Panel 3 is the date. This is usually the completion date and is inserted when the deed is finalised.
Panels 4–6: The people involved and where Land Registry will contact you
Panel 4 is the transferor (seller/current owner). Names must match the register, or evidence may be required.
Panel 5 is the transferee (buyer/new owner). It can include up to four people.
Panel 6 is the correspondence address for the transferee. This is important because Land Registry may send notices affecting your rights, and you can provide additional addresses such as email.
Panels 7–9: The “transfer”, price/gift, and title guarantees
Panel 7 is standard wording and isn’t normally changed.
Panel 8 covers consideration: the price, a gift, or another arrangement.
Panel 9 is title guarantee. Many transactions use full title guarantee, but limited title guarantee can apply in specific circumstances, and it carries legal meaning.
Panel 10: Declaration of trust (joint ownership)
If more than one person is buying, Panel 10 helps record whether you own as joint tenants or tenants in common, which affects inheritance and shares.
This is one area where misunderstandings can lead to disputes later, which is why many people prefer this to be handled carefully during the conveyancing process.
Panels 11–12: Extra terms and signing correctly
Panel 11 is for additional provisions such as covenants or agreements. These can be binding even after completion.
Panel 12 is execution (signing). Signatures must be witnessed properly, and a party to the transfer should not act as a witness for another party.
The TR1 form is one of the documents used during the conveyancing stage of a property purchase.
Need Help With a TR1 Transfer?
Our conveyancing solicitors can prepare and check the TR1 form, deal with the supporting documents and help keep your property transfer on track.
What Else Must Be Sent With the TR1 Transfer Form?
A TR1 transfer form is not normally submitted alone. The application to update the register depends on other documents, and missing items can mean the Land Registry rejects or delays registration.
In many cases, you’ll also need:
- Stamp Duty Land Tax certificate, if SDLT applies
- AP1 (for registered land) or FR1 (for first registration)
- Identity evidence, especially if you are not represented by a conveyancer
This is one reason people choose a solicitor-led conveyancing process: it reduces the chance of missing something that seems small but causes a big delay.
What Should Be Checked Before Signing?
Before the Land Registry TR1 form is finalised, your solicitor or conveyancer will usually check the title register and any restrictions.
The register may include restrictions or notices that must be dealt with before registration can proceed, and leasehold titles may require landlord consent or notification.
Mortgages matter too. If the property is mortgaged, lender consent or evidence of discharge is often required.
This is the kind of detail that sits behind the scenes in the conveyancing process, but it directly affects whether your registration completes smoothly.
If you need help checking title restrictions, mortgage requirements or signing details, contact us before the TR1 form is finalised.
Do You Need a Solicitor for a TR1 Transfer Form?
You don’t always legally have to use a solicitor. However, HM Land Registry guidance and many top-ranking sources stress that the help available is limited if you do it yourself, and lenders often insist on a professional if a mortgage is involved.
The reason is simple: once signed, a TR1 is a legally binding deed. One of the competitor references makes this point strongly: it’s enforceable and should not be taken lightly.
For most buyers and sellers, the safest route is to treat the TR1 transfer form as part of a professionally managed conveyancing process, rather than a standalone form.
How Long Does the Land Registry Part Take?
The TR1 is signed around completion, but the Land Registry update can take longer.
Top-ranking sources note that Land Registry backlogs can mean it takes weeks or even months for changes to appear on official records.
The practical point: your move can complete, and you can live in the property, but the register update may be visible later.
Common Mistakes That Cause Delays
Most delays are avoidable. The usual problems come from mismatched details, missing supporting documents, or signing mistakes.
Here are the errors that commonly cause issues:
- Names not matching the register or ID
- Incorrect ownership selection in the declaration of trust
- Missing AP1/FR1, identity evidence, or SDLT documents
- Witness details incomplete, or witness not independent
This is exactly why many people choose a solicitor-led conveyancing process. It’s not just convenience—it’s risk control.
Quick “Before You Sign” Checklist
If you want a simple final sense-check before signing the TR1 transfer form, use this:
- The property address and title number match the register
- Names are correct and consistent with ID
- Consideration (price/gift) is correctly stated
- Joint ownership choice is clearly understood
- Witness is independent and completes full details
If any of those points feel uncertain, it’s better to pause and ask than to sign and hope.
TR1 Transfer Form in the Conveyancing Process
So, what is the TR1 transfer form in real terms? It’s the deed that makes the ownership transfer official and supports the Land Registry update.
The Land Registry TR1 form is straightforward on the surface, but small details (ownership type, restrictions, mortgage requirements, execution rules) can have long-term impact.
If you want to reduce risk and keep your transaction moving, it helps to have a solicitor manage the full conveyancing process—from title checks to submission—so you’re not chasing Land Registry queries after completion.
If you’d like support, you can reach the team via the Contact Us page, or explore Services and the dedicated Conveyancing service to see how Versus Law handles transfers end-to-end.
Download TR1 Form
Ready to Complete Your Property Transfer?
Whether you are selling, gifting a property or transferring ownership, our conveyancing team can handle the TR1 process from preparation through to registration.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
PM Law closure: help if your conveyancing is stuck
Affected by the closure of PM Law? We can help get your conveyancing back on track
If you were buying, selling, remortgaging, or dealing with post-completion paperwork with PM Law (or one of its associated firms) and everything has suddenly gone quiet, you’re not alone.
The Solicitors Regulation Authority (SRA) has confirmed it was alerted to PM Law’s unexpected closure on 2 February 2026 and intervened into the firm on 4 February 2026.
That intervention has left many people mid-transaction—worrying about deadlines, deposit money, mortgage offers, exchange/completion dates, and whether crucial steps like Stamp Duty or Land Registry registration have been done.
Our conveyancing team can step in quickly, explain your options clearly, and help you move matters forward.
What does an SRA “intervention” mean for your case?
When the SRA intervenes, it takes possession of the firm’s files and client money, and (where relevant) closes the practice with immediate effect.
The SRA has appointed Gordons LLP as the intervention agent for PM Law.
It’s important to know that the intervention agent’s role is to secure files/money and manage the closure—they are not there to continue your conveyancing or act for you in the transaction.
In practical terms, that usually means:
- You will need to instruct a new solicitor to continue your matter.
- Your new solicitor can often start work using the paperwork you already have (emails, documents, contract pack, mortgage offer, etc.).
- Your file and any funds held may take time to be identified and released due to the volume of matters involved.
What to do right now (especially if you’re in a chain)
If your conveyancing was with PM Law, these are sensible next steps:
Write down all key dates
Exchange date (if exchanged), expected completion date, mortgage offer expiry, removal bookings, notice to landlord, and any contractual deadlines.
Gather what you already have
Examples: memorandum of sale, contract pack, searches, enquiries, mortgage offer, ID checks, completion statement, and any bank details you were given. The SRA specifically advises gathering your communications and documents as this may be enough for a new lawyer to begin progressing the work.
Tell your estate agent and the other side’s solicitors
Let them know you are appointing a new solicitor so they can pause chasing the previous firm and help keep the chain informed.
Be cautious with payment details
If you receive any late requests for funds or changed bank details, treat them carefully and verify independently with your new solicitor (this is a common scam risk in property transactions).
Conveyancing delayed due to PM Law’s closure?
If your transaction has stalled following the SRA intervention into PM Law, our conveyancing team can step in quickly to protect your position and keep your move progressing.
If you’ve exchanged contracts or completion is imminent
If you have already exchanged, timing becomes critical.
The SRA says its intervention agent is prioritising the most urgent matters (for example, where contracts have been exchanged), and in exceptional circumstances the agent may be able to act on an emergency basis—at their discretion—if completion is due within days of the intervention.
Even so, the safest route is usually to instruct a new conveyancing solicitor immediately so they can:
- assess where matters stand,
- liaise with the other side and your lender,
- and take urgent steps to protect you from breach of contract and avoid the chain collapsing.
If your transaction has stalled, it can help to understand the typical stages of a conveyancing transaction in the UK and where delays might occur.
How we can help
If you instruct us, we can:
- Review your situation fast (including how close you are to exchange/completion and any deadlines).
- Take over the conveyancing file and work with the other side’s solicitors, estate agents, and lenders to keep the transaction moving.
- Request your file from the intervention process where needed, and progress matters in the meantime using the documents you already have.
- Deal with post-completion issues (for example: confirming Stamp Duty submission/paid, Land Registry registration, title updates, lender registration).
- Explain options around client funds held by PM Law (including what the SRA says about tracing/returning money, and when a Compensation Fund application may be relevant).
What we need from you (checklist)
To help you quickly, please send (if you have them):
- Property address
- Whether you are buying/selling/remortgaging
- Your best estimate of where things got to (offer accepted? searches ordered? enquiries outstanding? exchanged?)
- Any target dates (especially exchange/completion)
- Estate agent details
- Mortgage lender and broker details
- Copies of emails and attachments from PM Law
- Any completion statement or request for funds you received
Don’t worry if you don’t have everything—many clients won’t. We can still advise and begin steps to stabilise the transaction.
Speak to our conveyancing team
If you’ve been affected by the closure of PM Law and need clear, practical help, contact us today and we’ll talk you through next steps.
Call: 0161 249 5087
Email: info@versuslaw.co.uk
If you have already exchanged contracts or completion is due soon, please mark your enquiry as URGENT.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
What does a conveyancing solicitor actually do?
A conveyancing solicitor is the person who makes sure your property move is legally safe, financially secure, and properly completed. Even when a sale looks straightforward, the legal side can hide surprises that only show up in paperwork.
If you’re buying, selling, or doing both in a chain, the work of a conveyancing solicitor often decides whether the move stays calm or becomes stressful. This guide explains the process in plain UK English, with clear stages and what you should expect.
What is a conveyancing solicitor?
A conveyancing solicitor is a qualified legal professional who handles the legal transfer of ownership when property is bought or sold. Their role covers contracts, legal checks, and the secure transfer of funds.
A conveyancing solicitor doesn’t just “process forms”. They protect you from legal risks like title defects, restrictions, or unresolved disputes that can delay completion or cause major problems later.
If you want a clear view of what full legal support includes, Versus Law outlines their conveyancing services in a helpful, easy-to-scan way.
Why their role matters more than people think
Most property issues are not visible during a viewing. They’re legal, documentary, or timing-related. A conveyancing solicitor checks what you can’t realistically verify yourself.
They also keep the transaction compliant with lender requirements, which is crucial if you’re buying with a mortgage.
A solicitor guides buyers and sellers through every stage of the transaction, which you can explore in our guide on what happens during the conveyancing process in the UK.
What does a conveyancing solicitor do for buyers?
For buyers, a conveyancing solicitor focuses on protecting you from legal and financial risk before you commit. They investigate the property’s legal status and confirm that the seller has the right to sell it.
They also make sure the contract terms are fair and that nothing important is missing from the legal pack.
Typical buyer tasks include:
- Reviewing the draft contract and title documents
- Ordering legal checks and reviewing results
- Raising enquiries with the seller’s solicitor
- Checking your mortgage conditions and lender rules
- Preparing you for exchange and completion
What “legal checks” really mean in practice
A conveyancing solicitor checks things like ownership boundaries, rights of way, and restrictions that affect how you can use the property. These details can impact renovations, resale value, or even your ability to get mortgage approval.
Even in a “normal” purchase, a solicitor may identify problems that allow you to renegotiate, request fixes, or decide not to proceed.
Before looking at the solicitor’s role, it helps to understand what conveyancing actually involves when buying property.
What does a conveyancing solicitor do for sellers?
For sellers, a solicitor prepares the paperwork and responds to legal questions quickly to keep the sale moving. This is where accuracy matters, because incomplete or unclear answers can stall a buyer’s progress.
A conveyancing solicitor also manages the sale funds safely, including paying off any mortgage you still have on the property.
Typical seller tasks include:
- Drafting the contract pack and issuing legal documents
- Guiding you through property information forms
- Answering buyer enquiries clearly and promptly
- Agreeing dates for exchange and completion
- Handling mortgage redemption and sale proceeds
Why sellers can accidentally cause delays
Delays often happen when documents are missing, answers are vague, or paperwork isn’t returned on time. A good conveyancing solicitor will chase what’s needed early and help you provide clean, consistent information.
Need help with your property move?
If you’re buying, selling, or facing a complex property transaction, an experienced conveyancing solicitor can guide you through every legal step. Our team explains your position clearly, highlights risks early, and helps keep your move on track — without unnecessary stress.
Speak to a conveyancing solicitor
The key stages: offer accepted to completion
A property move isn’t one event. It’s a sequence of legal steps that must happen in the right order, with the right documents, at the right time.
A conveyancing solicitor coordinates these steps so you don’t get caught by last-minute surprises.
Typical conveyancing stages:
- Offer accepted and you instruct your solicitor
- Draft contract and legal pack received and reviewed
- Enquiries raised and answered
- Mortgage conditions confirmed (if applicable)
- Exchange of contracts
- Completion and transfer of ownership
How long does it usually take?
Timeframes vary, but delays often come from third parties: managing agents (leasehold), slow responses, missing documents, or chains. A solicitor can’t control everything, but they can remove avoidable friction by starting early and chasing firmly.
If you want a quick estimate of likely legal costs in your situation, Versus Law provides a useful conveyancing calculator.
What happens at exchange of contracts?
Exchange of contracts is the moment the transaction becomes legally binding. Before exchange, either party can usually pull out. After exchange, backing out can lead to serious penalties.
A solicitor will only recommend exchange when the legal position is clear and you’re properly protected.
What your conveyancing solicitor checks before exchange
They make sure the contract is agreed, the important enquiries are resolved, and that you understand what you’re committing to. They also confirm that mortgage and deposit arrangements are ready.
This stage is where “rushing to meet a target date” can backfire. A careful solicitor protects you from exchanging too early just to satisfy pressure from a chain or an estate agent.
Leasehold vs freehold: why leasehold takes longer
Leasehold property transactions often require extra documents and third-party involvement. That alone can add weeks if the building manager is slow or if information is incomplete.
A conveyancing solicitor will examine lease terms and ongoing costs, not just the purchase price.
What your conveyancing solicitor reviews on leasehold
They’ll look closely at service charges, ground rent, restrictions, and the remaining lease length. They’ll also review management information and whether there are disputes in the building.
This work matters because lease terms can affect resale value and mortgage options. A conveyancing solicitor is there to spot red flags before you commit.
What affects conveyancing fees?
Conveyancing costs vary depending on complexity. The price isn’t only about the solicitor’s time. It can include third-party costs and additional legal checks required by lenders or the transaction type.
Common factors that increase cost or time:
- Leasehold property or managed buildings
- New builds with tight deadlines and extra documents
- Complicated chains with multiple parties
- Title issues, missing paperwork, or legal disputes
Why very cheap quotes can be risky
Low quotes sometimes exclude important work or add fees later. A good conveyancing solicitor will be transparent about what’s included and what could change.
The goal isn’t to find the cheapest option. It’s to find a conveyancing solicitor who keeps the process safe and moving.
How to choose the right conveyancing solicitor
Choosing a conveyancing solicitor is mainly about clarity and responsiveness. In property, delays usually happen because somebody doesn’t reply, doesn’t chase, or doesn’t explain things properly.
What to look for when comparing solicitors:
- Clear pricing with minimal hidden extras
- Fast response times and regular updates
- Experience with your property type (leasehold, new build, chain)
- Strong reviews that mention speed and reliability
If you want a sense of service quality from real clients, Versus Law’s testimonials are useful for reassurance.
Final thoughts: why your conveyancing solicitor matters
A conveyancing solicitor is your legal safety net during one of the biggest financial transactions you’ll ever make. They protect your money, your legal position, and your timeline.
Even if you’re confident and organised, there are legal risks you can’t see without a trained professional. That’s why having the right conveyancing solicitor is one of the smartest decisions you can make for a smooth move.
If you’re ready to ask questions or start the process, you can contact Versus Law for guidance tailored to your situation.
Ready to move forward with confidence?
Property transactions involve critical legal details that shouldn’t be rushed or overlooked. Whether you’re purchasing your first home, selling a property, or dealing with a tight timeline, our conveyancing solicitors provide clear advice, proactive communication, and dependable legal support from start to completion.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
What is conveyancing? A simple guide for first-time buyers
What is conveyancing? It is the legal process of transferring property ownership from the seller to the buyer. For many first-time buyers, understanding what is conveyancing helps reduce stress and avoid costly mistakes. Buying your first home is exciting, but the legal side can feel like a different language. That’s where conveyancing comes in.
What Is Conveyancing?
What is conveyancing? Conveyancing is the legal process that transfers ownership of a property from the seller to the buyer. It makes sure the property is legally “safe” to buy (for example, there aren’t hidden restrictions, boundary issues, unpaid charges, or lease problems that could affect you later).
When people ask what is conveyancing, they’re usually trying to understand two things:
- what checks happen before you’re committed, and
- how you get from “offer accepted” to “keys in hand” without nasty surprises.
Conveyancing covers the legal paperwork, the searches, the contract, the money transfer, and the final registration of you as the owner at HM Land Registry.
Who Handles Conveyancing and What Do They Do?
When people ask what is conveyancing, they are usually trying to understand who manages the legal work and why it matters. Most first-time buyers choose to work with an experienced conveyancing solicitor to handle these checks and protect their interests throughout the transaction.
Your conveyancer typically:
-
reviews the draft contract and title documents
-
orders searches (local authority, drainage, environmental, and others if needed)
-
raises enquiries with the seller’s solicitor (questions that must be answered before exchange)
-
checks your mortgage offer and acts for your lender (if you’re getting a mortgage)
-
explains key issues in plain English before you commit
-
handles exchange of contracts and sets the completion date
-
transfers the purchase money and receives confirmation you can collect keys
-
registers you as the new owner with HM Land Registry and deals with Stamp Duty (if applicable)
So if you’re still thinking what is conveyancing in practical terms: it’s the “legal safety net” that turns a handshake deal into legal ownership.
The Conveyancing Process Step-by-Step
Understanding what is conveyancing at each stage helps buyers know when they are legally committed. Below is a typical first-time buyer timeline. Some transactions move quickly, some take longer (chains, leaseholds, and slow management companies are the usual culprits).
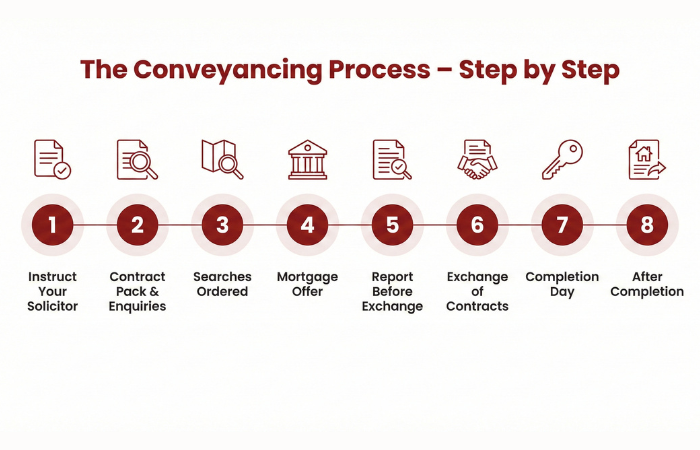
Step 1: Instruct your solicitor early
Once your offer is accepted, instruct your solicitor straight away. They’ll run ID and anti-money laundering checks and contact the seller’s solicitor for the contract pack.
During a property purchase, a solicitor handles the legal work, and you can learn more about the role of a conveyancing solicitor during a property transaction.
Step 2: Contract pack received and enquiries begin
The seller’s solicitor sends the draft contract, title information, and key property forms. Your solicitor checks everything and starts raising enquiries (for example: guarantees for building work, building regs sign-off, rights of way, boundaries, service charges, lease terms).
Step 3: Searches are ordered
Searches uncover issues you can’t see from a viewing. Common ones include:
-
Local authority search (planning permissions, enforcement notices, adopted roads)
-
Drainage and water search (sewers within boundaries, connection details)
-
Environmental search (flood risk indicators, contaminated land screening)
Depending on the location, your solicitor may recommend additional searches (mining, chancel repair, HS2/transport, etc.).
Step 4: Mortgage offer and lender requirements
If you’re buying with a mortgage, your solicitor checks the mortgage offer conditions and ensures the legal title is acceptable to the lender. This is one reason conveyancing can’t be treated as “just admin” — your lender has strict rules.
Step 5: Report to you before exchange
Once searches and enquiries are satisfactory, your solicitor will report to you. This is your chance to fully understand:
-
what you’re committing to
-
what risks exist (if any)
-
what documents you’ll be signing
-
how much money you must send and by when
Step 6: Exchange of contracts (you become legally committed)
Exchange is the point where the deal becomes legally binding. You pay your deposit (often 5–10%) and agree a fixed completion date.
This is the moment first-time buyers most need clarity, because after exchange you can’t simply “change your mind” without serious financial consequences.
Step 7: Completion day (you get the keys)
On completion, the remaining money is transferred to the seller’s solicitor. Once confirmed, the estate agent releases the keys.
Step 8: After completion (registration and final legal steps)
Your solicitor submits the Land Registry application to register you as the owner and deals with any Stamp Duty Land Tax requirements. Registration can take weeks or longer depending on Land Registry workload and transaction complexity.
If you’re new to property transactions, it helps to understand what happens during the conveyancing process in the UK step by step.
How Long Does Conveyancing Take?
Once you understand what is conveyancing, it becomes easier to see why timelines can vary. For many first-time buyers, conveyancing often takes around 8–12 weeks from offer accepted to completion, but it can be shorter or longer.
Typical reasons it takes longer:
-
a chain (multiple linked buyers/sellers)
-
slow search results from the local authority
-
leasehold paperwork delays (management packs are a common bottleneck)
-
outstanding enquiries (e.g., missing certificates, unclear boundaries)
-
mortgage offer delays or additional lender requirements
Conveyancing Costs Explained (So You Can Budget Properly)
A key part of understanding what is conveyancing is knowing which costs are legal fees and which are third-party charges. Conveyancing costs are usually split into two parts:
1) Legal fees (your solicitor’s fee)
This covers the solicitor’s professional work. Costs vary based on complexity (leasehold, new build, shared ownership, unregistered land, or a long chain can add work).
2) Disbursements (third-party costs)
These are payments your solicitor makes to others on your behalf, such as:
-
searches
-
Land Registry fees
-
bank transfer fees
-
Stamp Duty (if due)
If you’re comparing quotes, make sure you’re comparing like-for-like. A cheaper quote can sometimes exclude items that later appear as “extras”.
Freehold vs Leasehold: What First-Time Buyers Must Know
Freehold
You own the property and the land it stands on. Conveyancing is usually more straightforward.
Leasehold
You own the property for the length of the lease, but not the land. Leasehold conveyancing typically involves more checks, such as:
-
lease length (short leases can affect resale and mortgage availability)
-
ground rent terms and escalation clauses
-
service charges and planned major works
-
restrictions (pets, subletting, alterations)
-
management company performance and paperwork timelines
If you’re buying a flat, it’s often leasehold — so the conveyancing process can take longer and cost more.
Common Reasons Conveyancing Gets Delayed (And How to Reduce Them)
1. Slow responses to enquiries
If documents are missing (FENSA certificates, warranties, building regs approvals), your solicitor will ask for them. Sellers sometimes need time to locate paperwork.
What you can do: respond quickly to your solicitor, and keep pressure on the estate agent to chase the chain.
2. Searches take time
Local authorities vary widely in turnaround.
What you can do: instruct your solicitor immediately and ensure they order searches early.
3. Mortgage admin
Lenders may request extra documents, especially with gifted deposits or unusual properties.
What you can do: get your paperwork ready early (ID, deposit evidence, gifted deposit letter, bank statements).
Choosing the Right Conveyancing Solicitor as a First-Time Buyer
A first-time purchase is not the best time to gamble on poor communication. Look for:
-
clear, upfront pricing
-
a named point of contact (or a clear team structure)
-
proactive updates (not just “we’ll let you know”)
-
experience with first-time buyers and the type of property you’re buying (flat/house, leasehold/freehold)
If you’re unsure where to start, speaking to a solicitor early can help you understand timelines, costs, and potential risks before you commit.
Quick First-Time Buyer Checklist (Before You Start)
-
Have your ID and deposit evidence ready (especially if any deposit is gifted)
-
Instruct your conveyancing solicitor as soon as the offer is accepted
-
Arrange a survey early (even if the lender does a valuation)
-
Keep funds accessible for searches and the deposit
-
Reply to solicitor queries quickly to avoid avoidable delays
How Versus Law Can Help First-Time Buyers
It’s about explaining what matters, spotting issues early, and keeping the process moving with clear communication. Versus Law supports first-time buyers by handling the conveyancing process end-to-end, raising and resolving enquiries efficiently, and helping you understand the legal steps in plain English so you feel confident at each stage.
Need help with conveyancing?
Buying your first home can feel complex, especially when it comes to legal checks,
contracts, and completion timelines. Versus Law provides clear, practical conveyancing
support to help first-time buyers move forward with confidence.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
What is a gifted deposit and what proof is needed?
Buying your first home is exciting, but saving up for a deposit can feel like one of the biggest challenges. For many first-time buyers, help from family members can make all the difference.
This is where a gifted deposit often comes in.
A gifted deposit is very common in UK property purchases, but it does come with some important legal and mortgage requirements. Mortgage lenders and conveyancing solicitors will usually need proof of where the money has come from, and you must declare the gift properly to avoid delays.
In this guide, we explain what a gifted deposit is, what proof is needed, and how a conveyancing solicitor can help keep your purchase moving smoothly.
What is a gifted deposit?
A gifted deposit is money given to a home buyer (usually by a family member) to help fund the deposit needed to purchase a property.
The key point is that the money is a gift, not a loan. This means the person giving the money does not expect to be repaid and will not have any ownership rights in the property.
Example of a gifted deposit
A typical example might be:
- You are buying your first home for £250,000
- You need a 10% deposit (£25,000)
- Your parents gift you £15,000 to help you reach that amount
That contribution would be treated as a gifted deposit.
Gifted deposits are especially common for first-time buyers who may struggle to save while also paying rent and living costs.
When a gifted deposit is involved, a conveyancing solicitor will usually need to confirm the source of the funds and complete additional checks.
Is a gifted deposit allowed when buying a house in the UK?
Yes, a gifted deposit is completely legal in the UK, and mortgage lenders regularly accept them.
However, it must be properly declared as part of the conveyancing and mortgage process.
Mortgage lenders need to ensure that:
- The deposit is not actually a loan
- The gift will not create financial pressure on the buyer
- The funds come from a legitimate source
Your conveyancing solicitor is also required by law to carry out checks under UK anti-money laundering regulations.
So while gifted deposits are allowed, they must be handled correctly.
Why do mortgage lenders and solicitors ask for proof of a gifted deposit?
Many first-time buyers are surprised by how much paperwork is involved when using a gifted deposit.
This is mainly due to two reasons:
Mortgage lender requirements
Your lender needs to confirm that the deposit is genuinely a gift and not a loan.
If the deposit were repayable, it could affect your ability to afford mortgage repayments and may change the lender’s decision.
Anti-money laundering checks
Conveyancing solicitors must comply with strict UK anti-money laundering laws. This means we must verify:
- Who is providing the funds
- Where the money originally came from
- That the funds are not linked to criminal activity
These checks protect both buyers and the wider property market.
What proof is needed for a gifted deposit?
If you are using a gifted deposit, you should be prepared to provide certain documents early in the process.
Most mortgage lenders and conveyancing solicitors will ask for:
- A signed gifted deposit letter
- Bank statements showing the funds
- Proof of ID for the person gifting the money
- Evidence of the source of funds
- Confirmation that the gift is not repayable
- Any lender-specific gifted deposit forms
Providing these documents early can help prevent delays later on.
What is a gifted deposit letter?
A gifted deposit letter is a written document confirming that the deposit contribution is a genuine gift.
This letter is usually required by both the mortgage lender and your conveyancing solicitor.
What should a gifted deposit letter include?
A proper gifted deposit letter should confirm:
- The amount being gifted
- The name of the person providing the gift
- Their relationship to the buyer (e.g. parent, grandparent)
- That the money is a gift and not a loan
- That no repayment is expected
- That the giver will have no legal interest in the property
Your solicitor can help ensure the letter meets lender requirements.
Can a gifted deposit be repayable?
No, a gifted deposit must not be repayable.
If the money is expected to be paid back, it is no longer considered a gift. It becomes a loan, which could:
- Affect your mortgage affordability
- Require additional legal documentation
- Lead to the lender refusing the mortgage offer
It is always best to be honest and transparent with your solicitor and lender from the beginning.
Gifted deposits from overseas family members
It is possible for a gifted deposit to come from an overseas family member, but it often requires extra checks.
Mortgage lenders and solicitors may request additional documentation because international transfers can raise more questions about the source of funds.
Additional proof may include:
- Extra bank statements from overseas accounts
- Evidence of how the funds were built up (e.g. savings or property sale)
- Certified translations of documents
- Proof of the donor’s identity and address abroad
- Clear transfer records showing the money reaching the UK
Overseas gifted deposits are common, but it is important to plan ahead, as checks may take longer.
Common problems that cause delays
Gifted deposits can delay a purchase if the paperwork is not provided early.
Some common issues include:
- The buyer not telling their solicitor about the gifted deposit until late
- Missing bank statements or incomplete financial evidence
- The donor being unable to prove the source of funds
- Overseas transfers taking time to document
- Confusion over whether the money is a gift or loan
The sooner you disclose the gifted deposit, the smoother the conveyancing process will be.
How Versus Law can help
At Versus Law, we regularly assist first-time buyers using a gifted deposit.
Our experienced conveyancing solicitors can:
- Guide you through lender requirements
- Prepare and review gifted deposit letters
- Carry out anti-money laundering checks efficiently
- Help avoid delays before exchange and completion
- Support overseas gifted deposit cases with additional documentation
If you are buying your first home and receiving help from family, we are here to make the process clear and stress-free.
You can get started today by requesting a free conveyancing quote through our calculator:
https://www.versuslaw.co.uk/services/conveyancing/conveyancing-calculator/
Conclusion
A gifted deposit is one of the most common ways first-time buyers in the UK get help onto the property ladder.
While it is completely legal, mortgage lenders and solicitors will always require proof to confirm:
- The money is a genuine gift
- The funds come from a legitimate source
- The giver has no financial claim on the property
By providing the correct documents early, you can avoid unnecessary delays and keep your purchase on track.
For friendly, expert support with gifted deposits and the full conveyancing process, contact Versus Law today and request your free quote online.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
Buying a property with a sitting tenant: legal risks, rights & what buyers must know
On paper, buying a property with a sitting tenant can look like the ideal investment. The rent is already being paid, there is no void period, and there is no need to find tenants immediately after completion.
However, once you look beyond the surface — particularly with major changes to UK landlord law on the horizon — purchasing a property with a tenant in situ requires careful legal and financial consideration. You are not just buying a property; you are stepping directly into an existing legal relationship that may be difficult, slow, or costly to unwind.
Here is what you need to know before committing to a purchase with a sitting tenant.
What Is a Sitting Tenant?
A sitting tenant, also referred to as a tenant in situ, is someone who occupies a property at the point it is sold and continues living there after completion.
From the moment you complete the purchase, you become the landlord, inheriting:
-
The existing tenancy agreement
-
All statutory landlord obligations
-
Any historical compliance issues
There is no reset or renegotiation unless the tenant agrees. You take the tenancy exactly as it stands — for better or worse.
This can suit buyers seeking immediate rental income, but it can significantly limit flexibility if you intend to regain possession in the future.
Why Buying with a Sitting Tenant Is Riskier Than It Used to Be
The legal landscape for landlords is changing, and buyers must factor this into any decision involving a sitting tenant.
The Renters (Reform) Bill – What Is Changing?
The proposed Renters (Reform) Bill (also known as the Renters’ Rights Bill) is expected to introduce sweeping reforms to the private rented sector, including:
-
The abolition of Section 21 “no-fault” evictions
-
All Assured Shorthold Tenancies (ASTs) converting to periodic tenancies
-
Possession only being possible on specific, evidenced grounds
-
Increased court scrutiny and higher thresholds for eviction
-
Ongoing court delays making possession slower and less predictable
In practical terms, buying a tenanted property now means accepting that regaining possession may not be quick, easy, or guaranteed.
Not All Sitting Tenants Are the Same
A key risk for buyers is assuming that all sitting tenants are on modern Assured Shorthold Tenancies. This is not always the case.
Assured Shorthold Tenancies (ASTs)
Most sitting tenants will occupy the property under an AST that has rolled into a periodic tenancy. While current law allows eviction using Section 21 or Section 8, this position is expected to change significantly under the Renters (Reform) Bill.
Rent Act Tenants (Pre-1989)
If the tenant moved into the property before 15 January 1989, they may be protected under the Rent Act 1977.
These tenancies offer:
-
Long-term security of tenure
-
Rent control under a “fair rent” regime
-
Very limited grounds for possession
In reality, this means the tenant could remain in the property indefinitely, even if you wish to sell, redevelop, or move into the property yourself.
Your Responsibilities as the New Owner
When you buy a property with a sitting tenant, you take on full landlord responsibilities from day one, including:
-
Rent collection and management
-
Repairs and maintenance
-
Gas safety certification
-
Electrical safety compliance
-
EPC requirements
-
Deposit protection compliance
-
Right to Rent checks
If any of these obligations were mishandled by the previous landlord, you may still inherit the legal consequences.
This makes thorough legal due diligence essential.
Key Questions You Should Ask Before Exchange
Before committing to a purchase with a sitting tenant, you should ensure you have clear answers to the following:
-
What type of tenancy is in place?
-
Is the tenant paying rent on time?
-
Are there any disputes or arrears?
-
Is the tenant’s deposit correctly protected?
-
Are all safety certificates valid and up to date?
-
Has any eviction notice already been served?
-
Is the rent in line with market value or subject to control?
The answers will directly affect your rights, the property’s value, and your long-term investment return.
How a Sitting Tenant Can Affect Property Value
A property sold with a sitting tenant will usually command a lower price than one sold with vacant possession.
In some cases — particularly where the tenancy is long-standing or rent is regulated — the reduction in value can be significant. Discounts of 20% or more have been seen in certain parts of the UK.
For investors seeking long-term rental income, this may present an opportunity. For buyers who require flexibility, it represents a material risk that should be reflected in the purchase price.
Mortgage and Financing Considerations
Financing a property with a sitting tenant can be more challenging.
Many lenders are cautious when it comes to properties with:
-
Sitting tenants
-
Regulated tenancies
-
Below-market or controlled rents
As a result, cash buyers are often preferred, although some buy-to-let lenders may be willing to lend depending on the circumstances.
You should confirm lender appetite before agreeing a purchase.
The Takeaway: Know Exactly What You Are Buying
Buying a property with a sitting tenant can be a sound investment — but only if you fully understand the legal and financial implications.
With increasing tenant protections, the removal of no-fault evictions, and tighter landlord regulation, you cannot assume that possession will be straightforward.
Before proceeding, you should:
-
Understand the tenancy you are inheriting
-
Assess the risks realistically
-
Price the property accordingly
-
Obtain specialist legal advice early
Because once you complete, you are not just a buyer — you are a landlord.
Even when a tenant is already living in the property, the purchase still follows the standard conveyancing stages required for transferring ownership.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
Why you should transfer property portfolio to a limited company
To transfer property portfolio to a limited company is a decision many landlords and property investors consider as their portfolios grow. While the process involves legal, financial, and tax considerations, it can offer long-term advantages for those planning to retain, grow, or reinvest their property assets.
This structure is often explored by landlords who are affected by higher-rate income tax, restrictions on mortgage interest relief, or who want clearer financial separation between personal and investment assets. Understanding how the company structure works in practice is essential before deciding whether it is the right option.
What It Means to Transfer Property Portfolio to a Limited Company
When you transfer a property portfolio to a limited company, ownership of the properties moves from you personally to a separate legal entity. Even if you own and control the company, it is treated as distinct from you for legal and tax purposes.
In most cases, the transfer is legally treated as a sale at market value. This has implications for stamp duty land tax and capital gains tax, which should be considered carefully before proceeding. However, the change in ownership structure also alters how rental income, expenses, and profits are taxed going forward.
How Ownership Changes After the Transfer
Once the properties are owned by a limited company, rental income belongs to the company rather than to you personally. The company becomes responsible for managing income, expenses, and liabilities, and it pays corporation tax on its profits.
As a director or shareholder, you then decide how and when to extract money from the company, whether through salary, dividends, or repayment of director’s loans. This flexibility is a key reason why many landlords consider moving to a company structure.
Why the Transfer Is Treated as a Sale
HMRC treats the transfer of personally owned property to a limited company as a disposal, even if you are transferring it to a company you control. This means the transaction is assessed at market value rather than the price you choose to transfer it for.
Because of this, stamp duty land tax may be payable by the company, and capital gains tax may arise personally. While these upfront costs can be significant, they are often weighed against the long-term tax efficiency a company structure can offer.
In most cases, the ownership transfer will still require a TR1 form to legally transfer the property title.
Why Landlords Decide to Transfer Property Portfolio to a Limited Company
Many landlords decide to transfer property portfolio to a limited company when their tax position as an individual becomes less efficient. This is particularly common for higher-rate or additional-rate taxpayers and for those planning to grow their portfolio over time.
A company structure can support a more strategic, business-focused approach to property investment.
Deeper Tax Benefits of Using a Limited Company Structure
One of the most important advantages of holding property within a limited company lies in how profits and expenses are treated for tax purposes.
Corporation Tax on Profits
Rental profits earned by a limited company are subject to corporation tax rather than personal income tax. Corporation tax rates are generally lower than higher or additional rates of income tax, which can result in more profit being retained within the business.
This retained profit can then be reinvested into new properties, used to reduce borrowing, or held within the company for future use.
Full Deduction of Allowable Expenses
A limited company can deduct a wide range of legitimate business expenses from its rental income before calculating taxable profit. This typically includes:
-
Mortgage interest and finance costs
-
Property maintenance and repairs
-
Letting agent and management fees
-
Professional fees, including legal and accounting costs
-
Insurance, utilities, and compliance costs
Because these expenses are deducted in full before tax, the company’s taxable profit can be significantly lower than the gross rental income.
Mortgage Interest Relief
Unlike individual landlords, limited companies are not subject to the same restrictions on mortgage interest relief. Interest costs are treated as a business expense, reducing taxable profits directly. For leveraged portfolios, this can make a substantial difference to net returns.
Control Over When You Pay Personal Tax
When properties are held personally, rental income is taxed in the year it is earned. In contrast, a company structure allows you to control when you extract profits, helping you manage personal tax exposure more effectively.
Greater Control Over Long-Term Planning
A limited company structure allows landlords to think beyond short-term income. Retained profits can be used strategically, whether for reinvestment, portfolio expansion, or future retirement planning.
For landlords who do not rely on rental income for immediate living expenses, this control can significantly improve long-term tax efficiency.
Clearer Financial Separation
Holding property within a company creates a clearer division between personal finances and investment assets. This separation can simplify financial management and provide additional protection, as liabilities generally sit within the company rather than personally.
This approach is often preferred by landlords treating property as a business rather than a side investment.
Financial Factors to Consider Before You Transfer
Before deciding to transfer property portfolio to a limited company, it is important to understand the financial implications involved.
Upfront Costs You Need to Plan For
Transferring properties into a company can involve several upfront costs, including:
-
Stamp Duty Land Tax based on market value
-
Potential Capital Gains Tax
-
Mortgage exit fees or refinancing costs
-
Legal and conveyancing fees
These costs should be assessed against the potential long-term benefits of the new structure.
Ongoing Financial Responsibilities
Running a limited company involves ongoing administrative responsibilities. These include preparing annual accounts, submitting corporation tax returns, and maintaining statutory records.
While this adds complexity, many landlords find that the improved tax efficiency and control justify the additional administration.
Practical Considerations Beyond Tax and Cost
Tax is not the only factor to consider. Mortgage availability, lender requirements, and future exit plans should all be reviewed carefully.
Limited company buy-to-let mortgages can differ from personal mortgages in terms of rates and criteria, and refinancing may be required as part of the transfer.
Administrative Commitments
Running a company involves more administration than owning property personally. Directors must ensure filings are completed on time and records are kept correctly.
When Transferring a Property Portfolio Makes Sense
A company structure may be more suitable if you plan to hold properties long-term, reinvest profits, or grow a larger portfolio. It is often less suitable for landlords with a single property or those relying on rental income as their main personal income source.
Each situation is different, and the decision should be based on both current circumstances and future goals.
The Legal Process of Transferring a Property Portfolio
The legal process involves standard conveyancing, similar to any property sale. This includes valuation, contract preparation, mortgage arrangements, and registration with HM Land Registry.
Working with experienced solicitors helps ensure the transfer is completed correctly and in line with regulatory requirements.
Final Thoughts
To transfer property portfolio to a limited company can offer meaningful tax and structural advantages, particularly for landlords operating at scale or planning long-term growth. However, it is not a one-size-fits-all solution.
The right decision depends on your tax position, portfolio size, financing arrangements, and future plans. Professional legal and tax advice is essential to ensure the structure aligns with your objectives and avoids unintended consequences.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
What goes in an auction legal pack?
Buying or selling property at auction is fast, legally binding, and unforgiving. Once the hammer falls, contracts are exchanged immediately — which is why understanding what goes in an auction legal pack is essential before bidding or listing a property.
An auction legal pack provides buyers with the legal information they are expected to rely on before the auction. If something is missed, the risk usually sits with the buyer, not the seller.
What Is an Auction Legal Pack?
An auction legal pack is a bundle of legal documents prepared by the seller’s solicitor for a property being sold at auction. It is usually made available online via the auctioneer’s website and forms the legal foundation of the transaction.
Unlike private treaty sales, buyers do not negotiate terms after the offer. Everything they are agreeing to is contained in the legal pack.
Is an Auction Legal Pack a Legal Requirement?
There is no strict legal rule requiring a seller to provide a full auction legal pack. However, in practice, most auction houses require one, and a property cannot realistically be sold without Special Conditions of Sale.
A minimal or poorly prepared pack often indicates unresolved legal issues. Experienced buyers treat this as a warning sign.
What Documents Are Included in an Auction Legal Pack?
While the contents vary, a professionally prepared auction legal pack in the UK will usually include the following core documents.
This documentation replaces much of the post-offer legal work typically carried out during residential conveyancing transactions.
Special Conditions of Sale
This document controls the transaction and overrides standard auction terms.
It typically confirms:
- Completion timescale (often 20–28 days)
- Whether VAT applies
- Additional costs payable by the buyer
- Occupation status
- Any overage or clawback clauses
Buyers who ignore this section often face unexpected costs or deadlines.
Title Register and Title Plan
The pack will include an Official Copy of the Register of Title and a Title Plan from HM Land Registry.
These documents confirm:
-
Legal ownership
-
Registered charges or restrictions
-
Rights of way and covenants
-
Legal boundaries of the property
Physical boundaries should never be assumed to match the legal title.
Supporting Deeds and Title Documents
If older conveyances or deeds are referred to on the title, they should be included in the legal pack. These often contain restrictions or rights that directly affect value or future use.
Missing documents here are a red flag.
Conveyancing Searches
Auction legal packs often include searches, but buyers must check whether they are current and sufficient.
Common searches include:
-
Local Authority Search
-
Drainage and Water Search
-
Environmental Search
-
Mining or ground stability reports (where relevant)
Outdated searches shift risk onto the buyer.
Property Information Forms
Depending on the property type, the pack may contain:
-
Property Information Form (TA6)
-
Fixtures and Contents Form (TA10)
-
Leasehold Information Form (TA7)
These forms disclose disputes, alterations, notices, and what is included in the sale. Ambiguous or “not known” answers should always be treated cautiously.
Lease and Tenancy Documentation
For leasehold or tenanted properties, the legal pack should include:
-
Lease agreements
-
Tenancy agreements
-
Rent details
-
Management information
-
Licences to assign or sublet
Buyers inherit tenants exactly as documented — not as verbally described.
Energy Performance Certificate (EPC)
An EPC is a legal requirement when selling property in England and Wales, including at auction. Missing EPCs can delay completion and expose sellers to penalties.
Why Reviewing an Auction Legal Pack Matters
Understanding what goes in an auction legal pack allows buyers to assess legal risk before bidding and helps sellers present a transparent, legally sound lot.
For buyers, it prevents costly surprises.
For sellers, it increases confidence, bidding activity, and completion speed.
Who Prepares an Auction Legal Pack?
Auction legal packs are usually prepared by the seller’s solicitor. However, auction transactions require specialist drafting — particularly for Special Conditions of Sale.
General conveyancing experience alone is not enough.
The legal documents included in the pack are typically reviewed by a solicitor acting for the buyer in an auction purchase.
How Versus Law Can Help
At Versus Law, our auction conveyancing solicitors advise buyers and sellers on
-
Reviewing auction legal packs before bidding
-
Identifying hidden legal and financial risks
-
Preparing compliant, buyer-ready legal packs
-
Auction-specific conveyancing strategy
In auction transactions, the legal work must be done before the hammer falls.
If you have any questions before requesting a quote, please contact us and our team will be happy to help.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?
OTHER NEWS
What is an LPE1 form?
If you’re navigating the world of leasehold property in the UK, you’ve probably come across the term LPE1 form. At first glance, it might sound like just another piece of legal jargon. But in reality, this humble document plays a massive role in the smooth (or not-so-smooth) transfer of ownership for leasehold properties. Whether you’re buying, selling, or simply trying to understand the process, the LPE1 form is something you can’t afford to ignore.
In simple terms, the LPE1 is a form that holds all the critical information about the leasehold structure of a property. It outlines things like ground rent, service charges, insurance, and any disputes or upcoming maintenance costs. Think of it as the property’s leasehold CV. Without it, conveyancing can grind to a halt, leading to delays, frustrations, and even collapsed sales.
This guide breaks down everything you need to know about the LPE1 form—from who completes it and how much it costs, to why it’s so important and how to handle it properly. So, whether you’re a buyer, seller, solicitor, or just curious about property processes, you’re in the right place.
What is an LPE1 Form?
The Leasehold Property Enquiries Form (LPE1) is a standardised questionnaire used in the buying and selling of leasehold properties in the UK. It was introduced to streamline the process of collecting essential leasehold-related information and make it easier for buyers and their legal teams to conduct due diligence.
The form is completed by the landlord, managing agent, or freeholder and then passed on to the buyer’s solicitor through the seller’s solicitor. It contains vital information on service charges, ground rent, major works, insurance, and much more. Essentially, it helps paint a full picture of what the buyer is getting into—not just the property itself, but the financial and legal obligations that come with the lease.
In a freehold transaction, much of this isn’t needed. But leasehold properties come with added layers of complexity, and the LPE1 helps remove the guesswork. It’s especially important for mortgage lenders too, as they need reassurance that the property won’t come with surprise financial risks.
History and Development of the LPE1 Form
Before 2013, leasehold property transactions were a bit of a wild west. Each solicitor had their own version of a questionnaire to get information from landlords or managing agents. The lack of standardization led to confusion, delays, and sometimes even legal disputes.
Recognising the need for clarity, the Law Society, in collaboration with other industry bodies like the Royal Institution of Chartered Surveyors (RICS) and the Council of Mortgage Lenders, created the LPE1 form. The idea was to make leasehold transactions simpler and faster by introducing a uniform document.
Since then, the form has undergone several revisions to reflect changes in property law and real-world challenges. For example, following the Grenfell Tower tragedy, updates were made to include fire safety questions and other critical building information. The aim was to enhance transparency and provide buyers with all relevant risks upfront.
Now, the LPE1 form is widely accepted as a standard part of the leasehold conveyancing process, helping to bring much-needed structure and predictability to an otherwise complex area.
Why is the LPE1 Form Important in Leasehold Transactions?
Buying a leasehold property isn’t as straightforward as purchasing a freehold. When you buy a leasehold, you’re essentially buying the right to live in a property for a fixed number of years—under a lease that comes with its own rules, restrictions, and costs. The LPE1 form helps buyers understand exactly what they’re stepping into.
Here’s why it’s so crucial:
-
Financial Clarity: It details ground rent, service charges, and any planned major works. This allows buyers to factor in ongoing and future costs.
-
Legal Assurance: Lenders need to see this form before they approve a mortgage. It reassures them that the property is a sound investment.
-
Avoiding Surprises: Nobody wants to buy a flat only to find out they owe thousands in unpaid charges or that the building is due for a costly roof replacement.
-
Faster Sales: Providing this document early on helps prevent last-minute hiccups and delays in the conveyancing process.
In short, the LPE1 form protects all parties—buyers, sellers, and lenders—by ensuring everyone is fully informed before a transaction goes through.
Who Fills Out the LPE1 Form?
The LPE1 form is usually completed by the managing agent, freeholder, or landlord responsible for the leasehold property. The seller initiates the process by instructing their solicitor, who then contacts the managing agent to request the form.
Here’s the typical workflow:
-
Seller instructs a solicitor to handle the sale.
-
Solicitor contacts the managing agent or freeholder.
-
The managing agent prepares the LPE1 form, often charging a fee.
-
Once completed, the form is sent back to the seller’s solicitor.
-
It’s then passed on to the buyer’s solicitor for review.
This is a key step in the conveyancing timeline, and delays often stem from this point—especially if the managing agent is slow to respond or waiting for payment before they start.
What’s Included in an LPE1 Form?
The LPE1 form is extensive and detailed. It covers a wide range of topics that fall under the leasehold umbrella. Here’s a rundown of the key information typically found in the form:
-
Lease Terms: Start date, duration, and expiry.
-
Ground Rent: Amount due, frequency, escalation clauses.
-
Service Charges: Historic and current charges, future budgets, payment status.
-
Reserve Fund/Sinking Fund: Whether it exists, current balance, purpose.
-
Buildings Insurance: Provider details, coverage, premium costs.
-
Disputes: Any known disputes between leaseholders and the landlord.
-
Major Works: Planned or proposed major works and how they’ll be funded.
-
Management Contacts: Who is responsible for the property management.
The form may also request supporting documents, such as:
-
Three years’ service charge accounts
-
Buildings insurance certificate
-
Fire safety reports
-
A copy of the current lease (if needed)
All of this helps the buyer’s solicitor assess whether the lease is secure, fair, and mortgageable.
Buying or Selling a Leasehold Property?
Our conveyancing solicitors can review the LPE1 form, identify leasehold risks and help prevent avoidable delays in your transaction.
Understanding Key Terms in the LPE1 Form
Leasehold properties come with their own language. Here’s a glossary of common terms you’ll see in the LPE1:
-
Ground Rent: An annual payment made by the leaseholder to the freeholder. It may increase over time based on the lease agreement.
-
Service Charges: Fees paid for the upkeep of communal areas—think gardens, hallways, lifts, etc.
-
Sinking Fund / Reserve Fund: A fund collected to pay for major future repairs.
-
Freeholder: The person or entity that owns the land on which the leasehold property sits.
-
Managing Agent: A company employed to manage the day-to-day running of the building.
-
Section 20 Notice: A legal notice served when major works are planned, usually when leaseholders will have to contribute over £250 each.
-
Arrears: Any unpaid service charges or ground rent.
Understanding these terms helps you make sense of the obligations you’re taking on—or passing to someone else.
How Long Does it Take to Get an LPE1 Form?
The average turnaround time is around 10 to 20 working days, but it can vary based on:
-
Responsiveness of the managing agent
-
Whether payment is required upfront
-
Complexity of the leasehold structure
Delays can occur if:
-
Multiple parties are involved (e.g., different agents for ground rent and service charges)
-
The managing agent is understaffed or inefficient
-
The seller doesn’t request the form early enough
To keep things moving, sellers should request the LPE1 as soon as their property is listed, not after an offer is accepted.
If you need help requesting or reviewing the form, contact us and our leasehold conveyancing team can advise you on the next steps.
How Much Does an LPE1 Form Cost?
Fees for an LPE1 form can range from:
-
£200 to £600+
And that’s per form. If your property has multiple managing agents or freeholders (common in shared ownership or complex developments), you may be required to pay multiple fees.
Why the fee?
-
Compiling the form takes time.
-
Agents often need to dig up historical financial records and attach supporting documentation.
-
It covers admin and compliance overhead.
Some agents offer a fast-track option—for an additional cost—if you’re in a hurry.
What Happens if You Don’t Provide an LPE1 Form?
Failure to provide an LPE1 can stall or even collapse the sale. Here’s why:
-
Solicitors won’t proceed without it.
-
Lenders may reject mortgage applications if the form is missing.
-
Buyers may pull out due to lack of information or fear of hidden charges.
If you’re a seller, this document is non-negotiable. If you’re a buyer, you should never proceed without reviewing it carefully.
Tips for Completing an LPE1 Form Accurately
Accuracy is everything. Mistakes or missing information can lead to delays or legal risks. Here’s how to ensure it’s done right:
-
Check all figures carefully—especially service charge and ground rent.
-
Include supporting documents like insurance schedules and accounts.
-
Use the most current version of the LPE1 form.
-
Respond to solicitor follow-ups promptly—they may need clarification.
Managing agents should treat the form with the same importance as any legal document—because that’s what it is.
Leasehold transactions also involve financial breakdowns such as the completion statement prepared before the purchase is finalised.
LPE1 vs LPE2: What’s the Difference?
You may have heard of an LPE2 form. It’s not a replacement, but rather a supplement to the LPE1.
-
LPE1: Standard form covering leasehold info for resale.
-
LPE2: Additional form providing details after a leaseholder has exercised their right of first refusal or right to manage.
Most transactions only require the LPE1. The LPE2 is more niche and used in specific legal scenarios.
How Buyers Should Interpret the LPE1 Form
Buyers shouldn’t just skim through the LPE1. Pay close attention to:
-
Rising ground rent clauses
-
Unpaid charges
-
Upcoming major works
-
Any Section 20 Notices
-
Short lease terms (e.g., under 80 years)
If any red flags appear, speak to your solicitor. Some of these issues can affect resale value or mortgage eligibility.
Recent Updates and Changes to the LPE1 Form
Recent versions of the LPE1 have been updated to include:
-
Fire safety and cladding disclosures
-
Better explanations of ground rent review clauses
-
Enhanced documentation checklists
Make sure you’re using the most current version by downloading it from the official Law Society website or confirming with your solicitor.
The LPE1 form might not be glamorous, but it’s an absolute powerhouse in leasehold transactions. It ensures transparency, speeds up conveyancing, and gives everyone involved the peace of mind they need to move forward. If you’re selling a leasehold, request it early. If you’re buying, review it carefully. And if you’re a solicitor or agent, treat it with the attention it deserves. After all, behind every smooth leasehold sale is a well-handled LPE1.
Need Help With an LPE1 Form?
Whether you are buying or selling a leasehold property, our conveyancing team can help obtain, review and respond to the information required for the transaction.
-
Do i need contents insurance?
-
5 ways to improve the value of your home
-
Your First Home scheme explained
-
Mould? What Mould? The AI Photos Fooling UK Home Buyers
-
What is the biggest mistake in a will?
-
Common conveyancing fees explained
-
Are conveyancing fees based on property value?
-
What does a conveyancing solicitor do during a property purchase?
-
What happens on exchange of contracts?
-
What’s the difference between exchange of contracts and completion?